14 Major Sea Routes: Chokepoints and Trade Stats (2026)

Updated: Oct 22

Table of Contents
QUICK ANSWER BOX: The 14 major sea routes of the world are: North Atlantic Route, Trans-Pacific Route, Europe–Asia Route (via Suez Canal), English Channel, Strait of Malacca, Strait of Hormuz, Panama Canal Route, Cape of Good Hope Route, Mediterranean Sea Routes, North Sea Routes, Red Sea Route, South China Sea Routes, Baltic Sea Routes, and Arctic Routes. The busiest sea route in the world by vessel count is the English Channel (Dover Strait), with 500+ ships per day. By cargo volume, the Trans-Pacific Route (200M+ tonnes/year) leads. By trade value, the North Atlantic Route ($600B+ annually) ranks first.
Around 80% of global trade by volume is carried by sea. The $14 trillion annual trade-economy figure is retained only as an estimate and requires a directly supporting source before publication.
In 2025, global maritime trade growth slowed. UNCTAD’s Review of Maritime Transport 2025 reports growth of 0.5% for 2025, compared with 2.2% in 2024. Suez Canal traffic was also severely affected by Red Sea security disruptions during 2025. In 2026, Hormuz and Red Sea developments continued to affect routing decisions and energy-market risk.
These are not abstract statistics. They determine what products reach your shelves, what fuel costs at the pump, and how global supply chains hold or break.
This article breaks down all 14 major sea routes: cargo volumes, transit times, chokepoints, and their current 2025–26 status.
Which Is the Busiest Sea Route in the World?
This is one of the most searched questions about maritime trade, and the answer depends on how you define "busiest."
By vessel count: The English Channel (Dover Strait) is the busiest sea route in the world. Over 500 ships pass through it every single day, more than any other waterway on earth. This vessel-count estimate needs a dated, direct source before publication. It connects the North Sea to the Atlantic Ocean and handles a constant flow of container ships, tankers, ferries, and car carriers.
By cargo volume: The Trans-Pacific Route carries over 200 million tonnes of goods per year, making it the highest-volume transoceanic corridor.
By trade value: The North Atlantic Route supports over $600 billion in annual trade between Europe and North America, the highest bilateral trade value of any sea corridor.
By container throughput: The Europe–Asia Route via the Suez Canal processes approximately 19.6 million TEUs per year under normal conditions, the largest single containerized trade lane in the world.
The confusion arises because different sources measure "busiest" differently. For an exam answer: the English Channel is the busiest sea route in the world by vessel traffic. For commercial shipping context, the Trans-Pacific and Europe–Asia routes carry more cargo by weight and value.
All 14 Routes at a Glance
Route | Cargo Volume | Transit Time | Key Chokepoint | 2025–26 Status |
1. North Atlantic | 150M+ tonnes/yr | 7–14 days | None major | ✅ Stable |
2. Trans-Pacific | 200M+ tonnes/yr | 12–16 days | Strait of Juan de Fuca | ✅ Stable |
3. Europe–Asia (Suez) | ~19.6M TEUs/yr | 20–25 days | Suez Canal | ⚠ Disrupted |
4. English Channel | 500+ ships/day | Hours | Dover Strait | ⚠ Congested |
5. Strait of Malacca | 23.2M bbl oil/day | 2–3 days | Malacca Strait | ⚠ Monitor |
6. Strait of Hormuz | ~21% global petroleum | Hours | Hormuz | 🔴 High tension |
7. Panama Canal | ~6% global trade | 8–10 hrs transit | None (capacity) | ⚠ Constrained |
8. Cape of Good Hope | Overflow/backup | +7–14 days vs Suez | None | ↑ Peak usage |
9. Mediterranean | 35M+ tonnes/yr | Days | Strait of Gibraltar | ✅ Stable |
10. North Sea | 30M+ tonnes/yr | Days | None major | ✅ Stable |
11. Red Sea | Significantly reduced | Days | Bab el-Mandeb | 🔴 Crisis |
12. South China Sea | 45M+ tonnes/yr | Days | Multiple disputed | ⚠ Monitor |
13. Baltic Sea | 30M+ tonnes/yr | Days | Danish Straits | ⚠ Sanctions impact |
14. Arctic Routes | 5M+ tonnes/yr | 30–50% shorter vs Suez | None established | 🔄 Emerging |
How Are the 14 Sea Routes Classified?
The 14 major sea routes fall into four categories.
Primary Routes are high-volume transoceanic corridors connecting the world's largest economies. The North Atlantic, Trans-Pacific, and Europe–Asia routes handle the bulk of global container and commodity trade.
Regional Routes support trade within and between continents, the Mediterranean, North Sea, South China Sea, and Baltic Sea corridors, each connecting dozens of smaller ports into larger trade systems.
Strategic Passages are the chokepoints: narrow waterways and canals that offer major time savings but carry systemic risk. The Strait of Malacca, Strait of Hormuz, Suez Canal, and Panama Canal all fall here. When one of these fails, the effects ripple globally within days.
Emerging Routes are corridors forming due to climate change. Arctic passages are the clearest example, shorter distances between Asia and Europe as sea ice retreats, but with serious infrastructure and geopolitical constraints still unresolved.
UNCTAD's 2025 report identifies geopolitical disruptions as the main driver of route changes today. The Red Sea crisis triggered the largest single route shift in recent maritime history, moving most Europe–Asia container traffic from Suez to the Cape of Good Hope, something not seen at this scale since the Suez Crisis of 1956.
The 14 Major Sea Routes: Full Analysis
1. North Atlantic Route (Europe–North America)

The North Atlantic Route is the world's highest-value trade corridor. It connects Europe's industrial centres with North American consumer and commodity markets, carrying approximately one-third of all global ocean traffic by cargo value.
Annual cargo volume exceeds 150 million tonnes, manufactured goods, automobiles, chemicals, grain. A typical voyage from Rotterdam or Hamburg to New York or Norfolk takes 7 to 14 days depending on seasonal weather and routing choices. The route supports over $600 billion in annual bilateral trade and handles more than 8 million TEUs each year.
There are no major chokepoints along this corridor. That single fact makes it one of the most operationally stable routes in the world, a meaningful advantage in a period when chokepoint disruptions are redrawing the map of global shipping.
For ship owners, the North Atlantic and Trans-Pacific are the two most active charter markets in container shipping, with freight rates tracked daily on the Baltic Exchange.
2025–26 status: Stable. No disruptions. Freight rates have firmed modestly on transatlantic lanes as capacity was pulled toward the Cape of Good Hope rerouting.
2. Trans-Pacific Route (Asia–North America)

The Trans-Pacific Route is the longest and one of the highest-volume trade corridors in the world. It connects Asia's manufacturing hubs, China, South Korea, Japan, Vietnam, Taiwan, with North American consumer markets, primarily through the ports of Los Angeles, Long Beach, Seattle, and Vancouver.
Average voyage distance: 6,000 to 8,000 nautical miles. Transit time: 12 to 16 days. The route carries over 200 million tonnes of goods annually. Electronics, textiles, automobiles, and consumer goods dominate the eastbound flow. Agricultural commodities and raw materials move westbound.
The key approach chokepoints are the Strait of Juan de Fuca on the US Pacific Northwest coast and the approaches to the Panama Canal for ships calling on East Coast ports via the all-water route.
2025–26 status: 2025–26 status: Operationally stable, but commercially disrupted. US tariffs introduced in early 2025, a 34% tariff on Chinese goods and 10% global import tariff, triggered a front-loading surge followed by a sharp demand drop. Freight rates on this corridor have been volatile throughout 2025 and into 2026, driven by trade policy uncertainty rather than route disruption.
3. Europe–Asia Route (via Suez Canal)

Under normal conditions, this is the most important container trade corridor in the world. The Europe–Asia route via the Suez Canal saves more than 10 days and thousands of miles compared to routing around Africa's Cape of Good Hope. In 2024, approximately 19.6 million TEUs moved from Asia to Europe on this corridor, 10.3% of all global container movements. Source required: add a dated, directly supporting container-trade dataset before publication.
The 2021 blockage by the Ever Given demonstrated how dependent global supply chains are on this single passage. Six days of blockage disrupted over $9.6 billion in daily trade. What followed in late 2023 was far worse in duration.
Since Houthi attacks began targeting commercial vessels in the Red Sea, most major carriers have rerouted via the Cape of Good Hope. By May 2025, Suez Canal tonnage was still approximately 70% below 2023 levels. Whether traffic returns to pre-crisis levels depends entirely on the resolution of the Yemen conflict, a situation that remains unresolved as of mid-2026.
2025–26 status: Severely disrupted. Most container lines still routing via Cape of Good Hope. Partial recovery expected only with a Yemen ceasefire. Egypt has expanded the southern section of the canal to improve capacity, but the security risk, not capacity, is the binding constraint.
4. English Channel Route , The World's Busiest Sea Route

Over 500 ships pass through the English Channel every day. No other waterway on earth sees that kind of vessel traffic. It is not a transoceanic corridor , it is a 560 km passage between southern England and northern France, connecting the North Sea to the Atlantic Ocean.
The reason for the density is simple geometry. Any vessel moving between North Sea ports , Rotterdam, Hamburg, Antwerp, Amsterdam , and anywhere in the Atlantic, Mediterranean, or beyond has to pass through here. There is no other route. So every ship that was ever going to use those ports, going anywhere south or west, ends up in the same narrow water. It narrows to just 34 km at the Dover Strait.
The Channel handles roughly a quarter of all goods entering the UK from the EU, and about a third of UK exports to the EU. The Dover-Calais ferry crossing , just 50 km , is one of the busiest passenger routes in the world, with over 16 million people and 5 million trucks passing through annually.
Traffic separation schemes (TSS) and IMO regulations enforce two-way traffic through the Strait of Dover. Despite this, the combination of high density, strong tidal currents, unpredictable weather, and vessels of all sizes sharing the same narrow water makes this one of the most operationally complex passages anywhere.
2025–26 status: Congested but stable. Post-Brexit customs friction continues to slow freight throughput between UK and continental European ports. No major incident disruptions.
5. Strait of Malacca (Southeast Asia Gateway)

The Strait of Malacca is the main gateway between the Indian Ocean and the Pacific Ocean, and the world's largest oil transit chokepoint by volume. In the first half of 2025, approximately 23.2 million barrels of oil per day passed through it, around 22% of global oil demand and 29% of all seaborne oil trade.
At its narrowest point , the Phillips Channel near Singapore, the strait is just 2.8 km wide. The collision and grounding risk at that width, with the volume of traffic passing through, is significant. Around 83,000 vessels transit annually.
Singapore sits at the eastern end and has built one of the world's most efficient transshipment hubs directly on the back of this strategic position. The alternatives, the Lombok Strait or Sunda Strait , add two to three days to a voyage, making diversion expensive for most operators.
Piracy remains a monitored risk, particularly in the approaches from the Andaman Sea. Regional navies and the cooperative Malacca Strait Patrol scheme have substantially reduced incidents from peak levels in the 2000s, but the threat has not disappeared.
2025–26 status: Operational, under monitoring. No major disruptions, but the concentration of traffic, 29% of global seaborne oil, means any incident here has immediate global consequences.
6. Strait of Hormuz (Persian Gulf Gateway)

The Strait of Hormuz is the most critical energy chokepoint in the world. Roughly 20–21% of global petroleum liquids pass through this passage connecting the Persian Gulf to the Gulf of Oman.
There is no practical alternative at anywhere near this volume. Saudi Arabia's East-West pipeline can handle some crude diversion, but it cannot replace Hormuz capacity. When Hormuz is threatened, it shows up in oil prices fast.
That repricing became acute in 2026. Following the outbreak of the US-Israel-Iran conflict on February 28, 2026, transit trade through Hormuz dropped sharply. According to IMF data tracked through March 2026, tanker transit volumes at the strait fell significantly from prior-year levels. JP Morgan had previously estimated that crude supply cuts could approach 12 million barrels per day if tanker transits were halted during peak disruption.
LNG transit through Hormuz essentially halted during the peak of the crisis, triggering a bidding war among Asian buyers for alternative supply. War risk insurance premiums on vessels transiting the strait reached up to 3% of vessel value , compared to around 0.25% just months earlier.
2025–26 status: High tension. The single highest-risk chokepoint in global shipping as of mid-2026. Naval presence from multiple countries has so far kept partial traffic flowing, but the strait remains the most geopolitically sensitive point in global energy trade.
7. Panama Canal Route (Pacific–Atlantic Connection)

The Panama Canal connects the Pacific and Atlantic Oceans through the Isthmus of Panama, handling approximately 13,400 vessel transits per year and facilitating roughly 6% of all global trade. The 2016 Neo-Panamax locks expansion increased capacity significantly, allowing vessels up to 14,000 TEUs to transit , giving US East Coast ports more direct access to Pacific cargo flows.
The canal's structural vulnerability is water. It relies on freshwater from Gatun Lake for its lock system. Extended droughts , increasingly frequent due to climate change , force transit restrictions that either reduce cargo loads or push ships to longer alternatives via Cape Horn or the Suez Canal.
In 2023 and 2024, severe drought conditions forced the Panama Canal Authority to restrict daily transits and maximum vessel draft. Ship transits in 2024 fell 42% from 2023 levels , a dramatic capacity reduction that added to global shipping disruption alongside the Red Sea crisis.
2025–26 status: Constrained. Transit volumes recovering from 2024 drought lows, but below pre-drought levels. Climate-driven water variability remains a structural risk that no engineering solution has fully addressed.
8. Cape of Good Hope Route (Africa Alternative)

Before late 2023, the Cape of Good Hope route was used primarily by bulk carriers and less time-sensitive cargo where avoiding canal fees was worth the extra distance. Since the Red Sea crisis, it has become the primary route for most container ships travelling between Asia and Europe.
The route adds approximately 3,000 to 5,000 extra nautical miles per voyage and 7 to 14 additional transit days. In 2025, Cape of Good Hope traffic reached its highest level in decades. South African ports , Durban and Cape Town , saw a sharp increase in bunkering, crew changes, and emergency repairs as ships made the longer southern passage.
For ship owners, routing around the Cape means more revenue days per voyage since ships spend more time at sea carrying cargo. This partially offsets higher fuel costs. The counterweight is severe weather risk in the Southern Ocean, particularly between June and August when storms are most frequent and wave heights can exceed 10 metres.
2025–26 status: ↑ Peak usage. The primary Europe-Asia container route as of mid-2026, a position it was never intended to hold at scale. Infrastructure at South African ports is being tested by the volume increase.
9. Mediterranean Sea Routes (Intra-Regional)

The Mediterranean forms a dense network for intra-regional trade connecting Europe with North Africa and the Middle East. It handles over 35 million tonnes of cargo annually , manufactured goods, agricultural products, energy, and ferry traffic.
The Western Mediterranean sees heavy container and ferry corridors along Barcelona–Genoa–Naples. The Eastern Mediterranean connects major hubs at Piraeus, Istanbul, and Izmir. The Strait of Gibraltar at the western end links the Mediterranean to the Atlantic; the Suez Canal at the eastern end connects it to the Indian Ocean and Red Sea.
The Mediterranean is a key energy corridor. North African oil, gas, and LNG move north to European markets through both pipelines and tanker routes. The port of Piraeus , heavily invested in by COSCO , has become a major container transshipment hub for cargo distributing across Southern and Eastern Europe.
2025–26 status: ✅ Stable. The western Mediterranean in particular has seen increased throughput as cargo previously routed through Suez now arrives via the Cape and enters the Mediterranean through Gibraltar.
10. North Sea Routes (Northern European Network)

The North Sea connects Northern Europe's industrial centres , Hamburg, Rotterdam, Antwerp, Amsterdam, Oslo, Copenhagen, Aberdeen , in a dense regional network. Annual cargo volumes exceed 30 million tonnes, dominated by energy, industrial goods, and general cargo.
The North Sea hosts substantial offshore oil and gas infrastructure. Regular supply vessel traffic serves drilling platforms and production facilities, particularly in the Norwegian and British sectors. This is also the centre of Europe's offshore wind expansion, with a growing fleet of installation and service vessels working in the southern and central North Sea.
Environmental regulations here are among the tightest in the world. The North Sea is an IMO Emission Control Area , low-sulphur fuel or scrubbers are mandatory. Adverse weather from October through March requires careful voyage planning.
2025–26 status: ✅ Stable. Offshore wind installation activity driving additional vessel demand in the region.
11. Red Sea Route (Middle East–Africa Connection)

The Red Sea connects the Indian Ocean to the Suez Canal through the Bab el-Mandeb strait at its southern end. In normal conditions it is the busiest corridor for container traffic between Europe and Asia, and a critical route for East Africa and Arabian Peninsula regional trade.
Those normal conditions ended in late 2023 and have not returned.
2026 update: Red Sea and Suez traffic has begun to recover from crisis-era lows, but flows remain below pre-crisis levels and the recovery is uneven by vessel type. Lloyd’s List Intelligence reported 1,228 Suez Canal transits in September 2026, 21% above September 2025 but 39% below pre-Houthi-crisis levels. Bab el-Mandeb recorded 1,215 transits in September, 16% above a year earlier but 47% below pre-crisis levels. Rerouting via the Cape of Good Hope adds distance and sailing time, tying up vessel capacity and potentially increasing fuel, schedule and insurance costs. The scale of these effects depends on route, vessel type, carrier decisions and changing security conditions; a rapid return to pre-crisis traffic should not be assumed.
2026 status: Recovery is underway, but the Red Sea remains exposed to renewed security threats and traffic remains below pre-crisis levels.
12. South China Sea Routes (Asian Integration)

The South China Sea handles over 45 million tonnes of cargo annually. It is the primary trade corridor between ASEAN nations and China, and a critical link in the supply chains of the electronics, automotive, and consumer goods industries. Just-in-time manufacturing networks in Taiwan, South Korea, Japan, Vietnam, and Malaysia depend on consistent, reliable transit through this sea.
It is also one of the world's most geopolitically contested waterways. Overlapping territorial claims between China, the Philippines, Vietnam, Malaysia, Brunei, and Taiwan create ongoing uncertainty. Military assets from multiple nations operate in the region. The presence of disputed island and reef constructions adds friction to what would otherwise be a straightforward high-volume trade corridor.
The Taiwan Strait, running through the western edge of the South China Sea, carries approximately 48% of the global container fleet annually. Any military escalation affecting Taiwan Strait transit would have immediate, severe consequences for global electronics supply chains.
2025–26 status: ⚠ Monitor. No direct commercial shipping disruption as of mid-2026, but territorial tensions have not reduced. Commercial operators maintain contingency routing plans.
13. Baltic Sea Routes (Northern European Integration)

The Baltic Sea connects Scandinavian and Baltic states , Sweden, Finland, Denmark, Estonia, Latvia, Lithuania, Poland, Germany , in an enclosed regional sea network. Annual cargo volumes exceed 30 million tonnes, covering forest products, paper, timber, machinery, and energy.
Winter ice conditions in the Gulf of Bothnia and Gulf of Finland require icebreaker support for ports like Helsinki and Stockholm from December through March. The Baltic is an IMO Emission Control Area , low-sulphur fuel or scrubbers are mandatory for all vessels.
EU sanctions on Russian trade following the 2022 Ukraine invasion significantly altered route patterns. Russian cargo flows through Baltic ports dropped sharply, while the scrutiny on vessels calling at Russian Baltic ports , particularly Primorsk, Ust-Luga, and St. Petersburg , intensified. The emergence of the shadow fleet to move sanctioned Russian oil has added a new layer of risk monitoring to Baltic Sea operations.
2025–26 status: ⚠ Sanctions impact. Established route patterns remain altered. Shadow fleet monitoring is ongoing.
14. Arctic Routes (Emerging Climate Corridors)
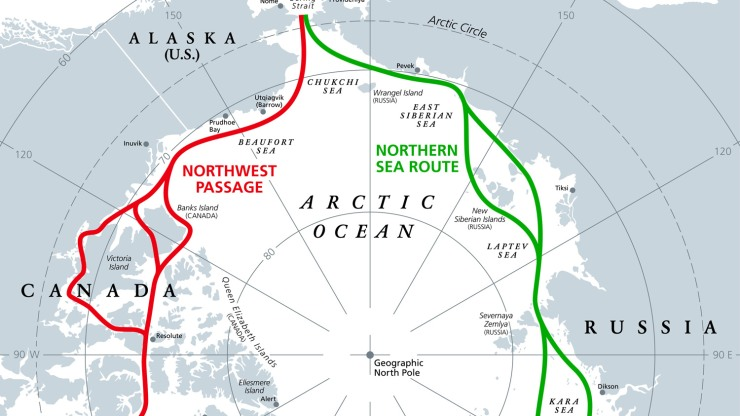
The Arctic Routes , primarily the Northeast Passage along Russia's northern coast and the Northwest Passage through the Canadian Arctic , are the most transformative emerging development in maritime geography. Annual cargo volumes now exceed 5 million tonnes and continue to grow.
The appeal is straightforward distance math. The Northeast Passage from South Korea to Rotterdam reduces the journey from approximately 21,000 km via Suez to roughly 13,000 km. That is 8,000 km fewer nautical miles per voyage , meaningful fuel savings at current bunker prices.
Getting there commercially is another matter. Vessels need ice-class certification and structural reinforcement. Icebreaker escort is mandatory for much of the route and controlled by Russia's Rosatom state corporation , which adds both cost and a geopolitical dependency most Western operators would rather avoid. Emergency response infrastructure along the route is essentially non-existent. International law around Arctic passage rights remains contested between Russia and much of the rest of the world. For most commercial operators, the Arctic is a 2030s option, not a 2026 one.
Climate change is accelerating the timeline. Sea ice is retreating faster than even pessimistic models predicted, and the seasonal navigation window is lengthening each year.
2025–26 status: 🔄 Emerging. Growing seasonal traffic, primarily LNG tankers and bulk carriers. Not yet commercially viable at scale for container shipping.
The World's Most Critical Maritime Chokepoints
A chokepoint is a narrow waterway that handles a disproportionate share of global trade, which creates systemic vulnerability. Any disruption at a chokepoint affects global supply chains within days. The five main chokepoints each present a specific type of risk.
Chokepoint | Daily Volume | Primary Risk | Alternative Route |
Strait of Hormuz | ~21% global petroleum liquids [3] | Iran–US geopolitical tensions | None comparable — limited Saudi Red Sea pipeline capacity |
Strait of Malacca | ~25% global oil | Piracy, collision risk | Lombok or Sunda Straits (+2–3 days) |
Suez Canal | ~12% global trade | Houthi attacks (2024–2026) | Cape of Good Hope (+7–14 days) |
Panama Canal | ~6% global trade | Drought-driven low water levels | Suez Canal or Cape Horn |
Bab el-Mandeb | Feeds Suez Canal | Active conflict zone (Yemen) | Cape of Good Hope (in use 2025) |
The article’s combined estimate that around 70% of global oil demand and more than 90% of seaborne oil trade pass through these five chokepoints needs a directly supporting source before publication; remove the combined-share claim unless a suitable source is supplied. The closure of even one has immediate, measurable consequences on energy prices, freight rates, and supply chain lead times.
2026 Status Update: Traffic Recovery and Chokepoint Exposure
As of 22 October 2026, global shipping routes remain exposed to geopolitical conflict, security risks and trade-policy uncertainty. Traffic through the Suez Canal is recovering, but Red Sea transit volumes remain below pre-crisis levels, while disruption around the Strait of Hormuz has increased uncertainty across energy and maritime supply chains.
1. Suez Canal and Red Sea traffic recovery
According to Lloyd’s List Intelligence’s 15 October 2026 update, the Suez Canal recorded 1,228 transits carrying 106.3 million deadweight tonnes (dwt) in September 2026. Transits were 21% higher year on year but remained 39% below pre-Houthi-crisis levels. Bab el-Mandeb recorded 1,215 transits carrying 95.6 million dwt, with traffic still 47% below pre-crisis levels.
The Suez Canal Authority’s reported figures also showed an increase in August 2026, when 1,358 vessels transited the canal, compared with 1,070 in August 2025. Reported canal revenue for August was US$567.1 million.
These figures indicate a recovery in traffic, not a complete return to normal. Conditions and transit patterns vary by vessel category and can change with security developments.
2. Strait of Hormuz and energy-shipping exposure
The US-Israel-Iran hostilities described in 2026 reporting have heightened concerns about the Strait of Hormuz, a critical route for global energy shipments. The supplied material reports reduced tanker transits, paused LNG flows and higher war-risk insurance costs. These specific claims including the reported insurance rate of 3% of vessel value, should be retained only if supported by dated, attributable sources verified before publication.
The interaction between Hormuz-related disruption and security risks in the Red Sea and Bab el-Mandeb creates overlapping risks for shipping schedules, energy supply chains, freight costs and route selection. Any claim that particular tanker flows diverted through the Red Sea should likewise be supported by a current source.
3. Trade-policy uncertainty and the wider outlook
Trade-policy changes, including US tariffs affecting China and other trading partners, have added uncertainty to global shipping demand and trade flows. Avoid presenting specific tariff rates or booking-volume changes as current 2026 facts without dated supporting sources.
The UNCTAD Review of Maritime Transport 2025 reported global maritime trade growth of 0.5% in 2025, compared with 2.2% in 2024. These are historical figures, not a forecast for 2026.
What this means for global sea routes
As of 22 October 2026, the key takeaway is that some Suez Canal traffic has recovered, while Red Sea security risks, Hormuz-related uncertainty and trade-policy changes continue to affect route planning. Vessel movements and exposure vary by ship type and cargo.
How Ship Owners Should Think About Route Exposure
Every commercial vessel operates on one or more of these 14 routes. The route a ship serves directly shapes its charter rate outlook, geopolitical risk exposure, seasonal demand patterns, and fuel cost profile.
Tankers are most exposed to Hormuz and Malacca disruption. A VLCC trading on the Middle East Gulf–Asia route passes through both. When Hormuz risk rises, war risk premiums on tanker voyages increase immediately.
Container ships on Europe–Asia lanes have faced a structural reroute. Ships that were running 20–25 day voyages via Suez are now running 30–35 day voyages via the Cape. That absorbs capacity , fewer round trips per year , which partially explains why container freight rates held up despite the demand softness of 2025.
Bulk carriers on Pacific routes , coal, iron ore, grain , have been relatively insulated from the Red Sea and Hormuz disruptions, since their primary trade lanes don't pass through either chokepoint.
Arctic exposure is today primarily relevant for LNG carriers and certain bulk cargo operators looking at Russia's Northern Sea Route. As the route develops commercially, more vessel segments will need to factor Arctic ice-class requirements into their investment decisions.
Frequently Asked Questions
What are the major sea routes of the world?
The 14 major sea routes are the North Atlantic, Trans-Pacific, Europe–Asia (via Suez), English Channel, Strait of Malacca, Strait of Hormuz, Panama Canal, Cape of Good Hope, Mediterranean, North Sea, Red Sea, South China Sea, Baltic Sea, and Arctic Routes. They carry approximately 80% of global trade by volume.
Which is the busiest sea route in the world?
The English Channel (Dover Strait) is the busiest sea route in the world by vessel count, with over 500 ships transiting daily. By cargo volume, the Trans-Pacific route leads. By trade value, the North Atlantic route ranks first.
How many sea routes are there in the world?
There are 14 widely recognised major sea routes. Beyond these, thousands of minor routes and regional shipping lanes connect smaller ports and coastal trade. The 14 major routes account for the overwhelming majority of global seaborne trade by volume and value.
Which sea route is most important for oil trade?
The Strait of Hormuz is the most critical. Approximately 21% of the world's petroleum liquids transit this passage daily. The Strait of Malacca is second , 23.2 million barrels per day, or 29% of all seaborne oil trade. Together, these two chokepoints control the flow of roughly half the world's traded oil.
What is the North Atlantic Sea Route?
The North Atlantic Sea Route connects Europe (ports like Rotterdam, Hamburg, Southampton) with North America (New York, Norfolk, Halifax). It carries over 150 million tonnes of cargo annually and supports more than $600 billion in bilateral trade. It is one of the most stable routes in the world, with no major chokepoints.
Why is the Red Sea route disrupted?
Since late 2023, Houthi militants based in Yemen have been attacking commercial vessels transiting the Red Sea and the Bab el-Mandeb strait. The attacks forced most major container lines to reroute via the Cape of Good Hope. By May 2025, Suez Canal tonnage was still 70% below pre-crisis levels. As of October 2026, traffic has recovered from crisis lows but remains below pre-crisis levels.
What is a maritime chokepoint?
A maritime chokepoint is a narrow waterway through which a disproportionate share of global trade passes. The five main chokepoints are Hormuz, Malacca, Suez Canal, Panama Canal, and Bab el-Mandeb. The combined share of global oil demand and seaborne oil trade needs a directly supporting source and should not be published without one. Disruption at any one of them has immediate global consequences.
What is the longest sea route in the world?
The Cape of Good Hope route between Asia and Europe, when used as an alternative to the Suez Canal, covers approximately 24,000 km , around 11,000 km longer than the Suez route. The Transpolar Arctic route, if commercially viable, would offer a much shorter alternative at approximately 13,000 km between South Korea and Rotterdam.
Glossary of Sea Route and Maritime Terms
Term | Definition |
Chokepoint | A narrow waterway through which a disproportionate share of global trade must pass, creating systemic vulnerability to disruption. |
TEU (Twenty-Foot Equivalent Unit) | The standard unit for measuring container ship cargo capacity. One TEU equals one 20-foot ISO container. |
Tonne-Mile | A unit of cargo transport work equal to one tonne of cargo moved one nautical mile. Used to measure effective fleet capacity utilisation. |
Suez Canal | A 193-kilometre artificial canal in Egypt connecting the Red Sea to the Mediterranean, eliminating the need to route around Africa. |
Strait of Hormuz | A 21-nautical-mile-wide waterway between the Persian Gulf and the Gulf of Oman through which approximately 20–21% of global petroleum liquids transit. |
Strait of Malacca | A narrow sea passage between the Malay Peninsula and Sumatra, narrowing to 2.8 km at the Phillips Channel near Singapore, carrying approximately 25% of global oil shipments between the Indian and Pacific Oceans. |
Cape of Good Hope Route | The sea route around the southern tip of Africa, used as the main alternative to the Suez Canal when the Red Sea is disrupted. |
Panama Canal | An artificial waterway across the Isthmus of Panama connecting the Pacific and Atlantic Oceans, handling approximately 6% of global trade. |
Bab el-Mandeb | A narrow strait between Yemen and Djibouti at the southern end of the Red Sea, forming the entry point to the Suez Canal route from the Indian Ocean. |
Northeast Passage | An Arctic sea route along the northern coast of Russia connecting the Atlantic and Pacific Oceans, navigable seasonally due to melting sea ice. |
Traffic Separation Scheme (TSS) | IMO-designated shipping lanes within busy waterways separating inbound and outbound traffic to reduce collision risk. |
Freight Rate | The price charged to transport cargo between two ports, expressed per TEU, per tonne, or as a daily hire rate for time charters. |
UNCTAD | United Nations Conference on Trade and Development. Publishes the annual Review of Maritime Transport — the primary global authority on seaborne trade statistics. |
EIA | U.S. Energy Information Administration. Publishes World Oil Transit Chokepoints data providing authoritative oil flow volumes through key maritime passages. |
Neo-Panamax | The larger lock class opened at the Panama Canal in 2016, accommodating vessels up to approximately 14,000 TEUs — significantly larger than the original Panamax locks. |
Baltic Exchange | A London-based marketplace that provides daily freight rate benchmarks for dry bulk, tanker, gas, and container shipping worldwide. |
Citations
Regulatory disclosure: Shipfinex FZCO holds VARA In-Principle Approval (IPA/26/01/002) for Virtual Asset Broker-Dealer Activity. This is an In-Principle Approval, not a full operational licence. Shipfinex is not authorised to commence operations or conduct virtual asset activities until it obtains final authorisation from the Virtual Assets Regulatory Authority (VARA). This article is for informational purposes only and does not constitute legal advice, regulatory guidance, or an offer or invitation to deal in virtual assets or securities.
All investments carry significant risk, including the potential for total loss. This is a high-risk asset. See the full Risk Disclosure Statement.

Capt. Anuj Chopra
Managing Director / Contributing Author
Capt. Anuj Chopra, ExC FNI FICS, is a maritime industry executive with over 40 years of experience. A former VP Americas at RightShip and co-founder of ESGplus LLC, he specialises in maritime risk, environmental compliance, and ESG. He also serves as an Adjunct Professor at the University of Houston and is a Fellow of both The Nautical Institute and the Institute of Chartered Shipbrokers.


