How Economics and Geopolitics Shape the Global Shipping Industry

Updated: 5 days ago
Key Takeaways
Shipping is driven by both trade demand and economic cycles. Freight rates, vessel capacity, fuel prices and port congestion influence the cost and efficiency of global maritime transport.
Geopolitical risk can reshape global trade routes. Conflicts, sanctions and maritime security threats can redirect vessel traffic, increase voyage distances and disrupt established shipping networks.
The Red Sea crisis demonstrated the economic impact of maritime chokepoint disruption. Rerouting vessels around the Cape of Good Hope increased sailing distances, affected vessel availability and contributed to freight-market volatility.
Longer voyages do not necessarily mean more cargo is being traded. UNCTAD reported that global maritime ton-miles increased by 5.9% in 2024, nearly three times the growth in cargo volume, reflecting the impact of longer shipping distances.
Trade wars and tariffs influence shipping demand and cargo flows. Changes in trade policy can affect sourcing decisions, manufacturing locations, port activity and demand across shipping routes.
The maritime energy transition involves more than choosing an alternative fuel. LNG, methanol, ammonia and hydrogen each have different production, emissions, safety, cost and bunkering infrastructure requirements.
Vessel capability and fuel infrastructure must develop together. The growth of alternative-fuel-capable vessels does not automatically mean that suitable bunkering facilities are available across their trading routes.
Shipping disruption affects more than freight rates. Fuel consumption, insurance conditions, vessel utilization, voyage duration and regulatory compliance also influence maritime operating costs.
Table of Contents
The global shipping industry is central to international commerce. It transports raw materials, energy resources, food, manufactured goods and consumer products between countries. According to UNCTAD, maritime transport remains the backbone of global trade, connecting producers, suppliers and consumers through an extensive network of ports, vessels and shipping routes.
The industry’s scale is supported by a diverse fleet, ranging from small general-cargo vessels to large container ships, bulk carriers, tankers and specialized vessels. Each segment responds to different cargo requirements, trading patterns, operating costs and market conditions.
The intricate interplay between economics and geopolitics is a central theme in the evolving landscape of the global shipping industry. These interconnected forces shape the industry's structure, operations, investment requirements and sustainability.
Economics influences shipping through trade demand, freight rates, fuel prices, vessel supply and operating costs. Geopolitics adds complexity by influencing trade policies, sanctions, maritime security, access to ports and the availability of shipping routes.
This article examines how these forces shape the shipping industry, from the historical impact of containerization and changes in ship propulsion to trade policy tensions, regional conflicts and maritime security developments. It also considers how these factors affect shipping operations and the assessment of vessel-backed assets.
Economics:
Global Trade and Containerization
Global trade has enduring historical significance for the shipping industry. For centuries, maritime routes have connected nations and enabled the exchange of goods, resources and cultures. The historical evolution of shipping is closely linked to changes in trade patterns, reflecting the expansion and contraction of global commerce.
The transformative impact of containerization cannot be overstated. In the mid-20th century, the standardisation of shipping containers changed cargo handling and port operations. Uniform steel containers made cargo transfer more efficient and reduced the time and labour associated with loading and unloading.
Containerization brought several operational advantages. It improved cargo handling, increased the volume of goods that could be transported, and provided greater protection against damage and theft. Standardised containers also made it easier to transfer cargo between ships, trains and trucks.
These changes helped reduce transport costs and enabled shipping companies to operate at greater scale. Containerization became a foundation of modern global supply chains, connecting manufacturing centres with consumer markets across continents.
However, container shipping economics remain sensitive to changes in demand, vessel capacity, port congestion, fuel prices and freight rates. When demand increases faster than available vessel capacity, freight rates may rise. When capacity exceeds demand, carriers may face pressure on utilisation and earnings.
The relationship between trade growth and shipping profitability is therefore not automatic. Vessel supply, fleet deployment, operating costs and market conditions all influence financial performance.
Ship Propulsion Through the Economic Lens

As one of my university professors, a former sailor, once said, profitability is at the core of any business venture, and shipping is no different.
Historically, steam engines were a primary choice for powering ships during the 19th and early 20th centuries. These engines used steam generated by boiling water to drive turbines or pistons, which turned the ship's propellers. However, steam propulsion had limitations, including fuel inefficiency, high maintenance requirements and dependence on coal or oil.
The transition from steam to internal combustion engines marked a significant turning point. Diesel engines offered greater fuel efficiency, operational reliability and flexibility. This transition helped improve vessel performance and reduce operating costs, making diesel propulsion a central feature of modern commercial shipping.
Today, the industry faces another transition: reducing greenhouse gas emissions while maintaining the economic and operational performance of vessels. The International Maritime Organization's greenhouse gas strategy and associated regulatory measures have increased attention on energy efficiency, alternative fuels and emissions reduction.
The search for alternative fuels includes liquefied natural gas (LNG), methanol, ammonia and hydrogen. Each option has different technical, economic, safety and infrastructure considerations.
LNG is used by a growing number of commercial vessels and can reduce certain air pollutants compared with conventional marine fuels. However, its lifecycle greenhouse gas performance depends on factors such as methane leakage, fuel production and onboard engine technology. LNG should therefore not automatically be treated as a zero-carbon solution.
Methanol is another alternative being adopted in new vessel designs. It can be stored and handled as a liquid under less demanding conditions than some other alternative fuels. Its overall emissions profile depends on how it is produced: fossil-based methanol and renewable methanol do not have the same lifecycle impact. Availability, production costs and bunkering infrastructure remain important considerations.
Ammonia is being developed as a potential low-carbon or zero-carbon fuel at the point of use, depending on the production pathway. Its adoption faces challenges relating to toxicity, safety, engine technology, fuel handling and limited bunkering infrastructure.
Hydrogen is also being considered for selected maritime applications. It has potential for low-emission propulsion when produced using low-carbon energy, but storage, transport, onboard systems and infrastructure present significant technical and economic challenges.
The development of these fuels is not only an environmental issue; it is also an investment and operating-cost consideration. Vessel owners must assess fuel availability, retrofit requirements, engine compatibility, vessel life, regulatory exposure and the potential cost of future compliance.
The infrastructure gap remains material. Lloyd's Register reported in November 2026 that 1,942 alternative-fuel-capable vessels were on order in January 2026, representing 47% of global orderbook tonnage. However, its report identified LNG bunkering at 222 ports, methanol bunkering at 25 ports and only one completed commercial ammonia bunkering operation at that time. The figures illustrate the difference between vessel capability and the availability of fuel infrastructure.
The transition towards cleaner fuels is therefore not a simple replacement of one fuel with another. It involves capital expenditure, technology choices, fuel supply chains, safety standards and the development of port infrastructure.
Globalization and Supply Chains
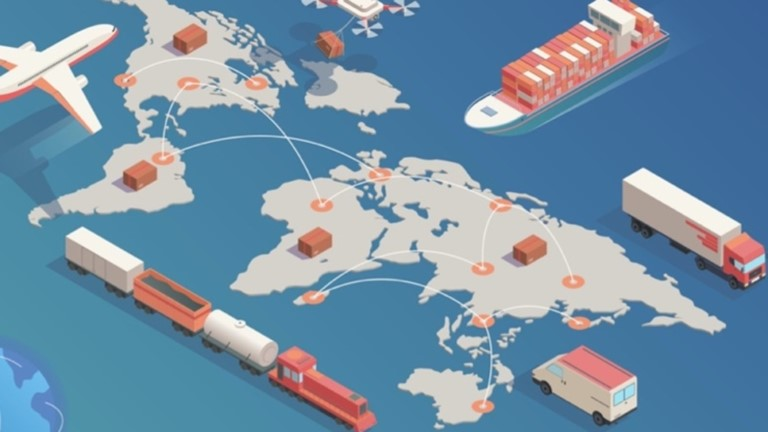
When it comes to globalization, the shipping industry assumes a central role. It connects manufacturers with suppliers and consumers across the world, supporting the movement of goods through complex international supply chains.
Everyday products such as smartphones, machinery, fertilisers and food grains depend on networks of production and distribution that may span several countries.
Smartphones, for instance, demonstrate the globalized nature of modern manufacturing. Product design, semiconductor fabrication, component manufacturing, assembly and distribution can take place in different countries. Shipping containers connect many of these stages, moving components and finished products between production centres and consumer markets.
The impact of globalization on shipping economics is significant. The pursuit of efficiency, cost-effectiveness and market reach has created complex logistics and transportation networks. These networks depend on predictable shipping schedules, port access, reliable trade routes and the availability of vessel capacity.
However, globally distributed supply chains can also create vulnerabilities. Disruption at a major port, canal or maritime chokepoint can affect production and delivery schedules across multiple markets. Companies may respond by diversifying suppliers, increasing inventory, changing transport routes or using alternative ports.
These adjustments can improve resilience but may also increase logistics and procurement costs. Supply chain efficiency and supply chain resilience are therefore related but distinct objectives.
Powering the Global Economy Post-COVID-19
The COVID-19 pandemic delivered a significant shock to the global economy and shipping industry. Lockdowns, port restrictions, labour shortages and changes in consumer demand disrupted established trade patterns.
The pandemic exposed the vulnerability of global supply chains to sudden interruptions. Port congestion, container shortages and changes in cargo demand contributed to substantial volatility in freight markets.
The container sector experienced exceptionally strong freight rates and earnings during parts of 2020 and 2021. Increased demand for goods, shifts in consumer spending and constrained shipping capacity contributed to the market conditions. These outcomes were not uniform across all shipping segments.
The pandemic also affected the cruise industry, where travel restrictions and health concerns resulted in widespread operational suspensions. Cruise operators faced a different set of commercial pressures from those experienced by container carriers, bulk shipping companies and tanker owners.
The post-pandemic period demonstrated that shipping performance depends on more than global trade volumes. Vessel availability, port efficiency, inventory strategies, fleet deployment and the balance between cargo demand and shipping capacity all influence market outcomes.
The experience also encouraged businesses to reassess supply chain resilience, including their dependence on individual suppliers, ports and transport corridors.
Geopolitics
Trade Wars and Free Trade Agreements
A trade war is a period of heightened economic conflict between two or more countries, often characterized by retaliatory tariffs, trade restrictions and other policy measures.
These measures can disrupt established trade relationships, increase costs for importers and exporters, and influence the movement of goods between countries. For shipping companies, changes in trade policy can alter cargo volumes, trade routes, vessel deployment and demand for shipping capacity.
Trade policy developments between major economies are particularly relevant to shipping because changes in tariffs and restrictions can affect large manufacturing and consumer markets.
The World Trade Organization reported that approximately 72% of global merchandise trade was conducted on most-favoured-nation (MFN) tariff terms at the end of July 2026, down from 80% at the beginning of 2025. MFN treatment is a non-discrimination principle under which a trade advantage granted to one WTO member is generally extended to other members. It does not mean that the trade is free from tariffs, restrictions or other trade measures.
Free Trade Agreements (FTAs), by contrast, establish preferential trading arrangements between participating economies. Examples include the United States-Mexico-Canada Agreement (USMCA), the Comprehensive Economic and Trade Agreement between Canada and the European Union (CETA), and the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP).
These agreements may reduce or eliminate tariffs on qualifying goods, streamline customs procedures and establish rules governing cross-border trade. Their effects on shipping depend on the goods covered, rules of origin, participating markets and changes in trade flows.
For shipping companies, both trade restrictions and trade agreements can influence cargo demand and route economics. However, the effect is not always immediate or uniform. Businesses may change sourcing locations, adjust inventory strategies or shift production between markets in response to policy changes.
Historical Conflicts and Their Effects on Shipping
Geopolitical conflicts have long affected maritime trade. The Middle East, the Black Sea, the Persian Gulf and the South China Sea are among the regions where political and security developments can influence shipping routes and commercial operations.
The Strait of Hormuz, for example, is a strategically important passage for global energy trade. Disruption in the strait can affect oil and gas transportation, tanker operations, energy prices and shipping risk assessments.
Vessels operating in areas exposed to conflict may face security threats, changes in insurance conditions, additional voyage costs or restrictions on port access. Shipowners and charterers must assess these risks alongside commercial considerations such as freight rates, fuel consumption and vessel utilisation.
The economic consequences can extend beyond the immediate conflict zone. Longer routes may increase voyage duration and fuel consumption. Disruption to energy exports can influence commodity prices, while changes in trade flows can affect vessel demand across different shipping segments.
The effects are not identical for every vessel. A tanker, container ship and dry bulk carrier may have different exposure depending on cargo, route, charter arrangements, ownership, flag and insurance conditions.
Russia-Ukraine War
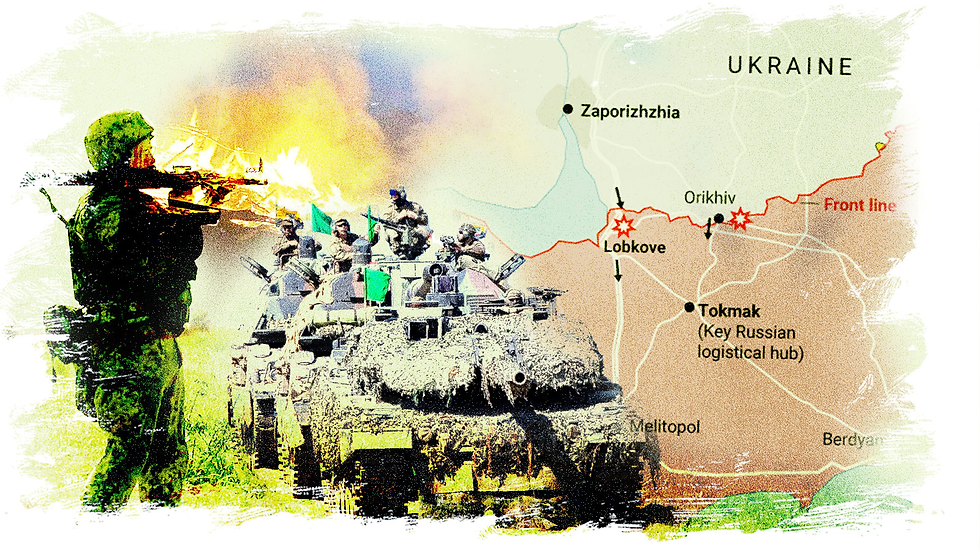
The Russia-Ukraine war has had significant consequences for international trade, energy markets and maritime logistics.
The conflict disrupted established Black Sea trade flows, including exports of grain and other agricultural commodities from Ukraine. Damage to infrastructure, restrictions on port operations and security risks affected the movement of cargo through the region.
The Black Sea Grain Initiative, brokered with the involvement of the United Nations and Türkiye, enabled the movement of Ukrainian agricultural exports through designated maritime corridors for a period. Its termination in July 2023 changed the operating environment for grain shipments and increased uncertainty around Black Sea trade.
The conflict also affected energy markets. Sanctions, changes in trade relationships and adjustments to energy sourcing altered the movement of Russian oil and other commodities. These changes influenced tanker routes, cargo destinations and the role of maritime services providers.
The shipping industry has had to account for sanctions compliance, cargo origin, vessel ownership, insurance coverage and the risk of prohibited transactions. These considerations can be complex where vessels, cargoes, counterparties and service providers are connected to multiple jurisdictions.
The Black Sea Grain Initiative is now a historical example of how diplomatic arrangements can affect maritime access and cargo flows. It should not be treated as a current operating framework.
The broader lesson is that geopolitical conflict can alter the geography of trade. Shipping companies may need to reassess routes, counterparties, insurance arrangements and compliance processes as conditions change.
Russian Oil Price Cap and Maritime Sanctions
The Russian oil price cap was introduced by the G7, the European Union and Australia in response to Russia's full-scale invasion of Ukraine. The policy was designed to limit Russian oil revenue while maintaining the availability of Russian oil in global markets.
The original price cap for Russian seaborne crude oil was set at USD 60 per barrel and took effect in December 2022. The framework links access to certain maritime services, including insurance and shipping-related services provided by coalition participants, to compliance with the applicable price cap and associated requirements.
The price cap is not a universal prohibition on transporting Russian oil. Its application depends on the relevant jurisdiction, service provider, cargo, transaction and applicable sanctions rules.
The European Union's framework sets a cap of USD 47.60 per barrel for Russian crude oil, USD 45 for discounted petroleum products and USD 100 for premium petroleum products. These are EU framework figures and should not be assumed to apply identically under every jurisdiction's laws. In July 2026, the EU also paused the automatic adjustment of its oil price cap mechanism until July 15, 2027.
The EU's July 2026 sanctions package also listed 41 additional vessels in connection with its measures targeting Russia's shadow fleet, on top of 632 vessels already listed at that time. The package extended measures to certain entities and service providers supporting shadow-fleet operations. These are EU measures, not a universal vessel blacklist.
Sanctions compliance can require shipowners, charterers, insurers, brokers and other maritime service providers to assess cargo pricing, counterparties, ownership structures, documentation and transaction records.
The use of complex ownership arrangements, ship-to-ship transfers and incomplete or inaccurate documentation can create compliance risks. Vessel identity and trading history may also require scrutiny when assessing potential exposure to sanctions or restrictions.
For shipowners and investors, sanctions exposure is not simply a geopolitical headline. It can affect a vessel's ability to trade, obtain insurance, access ports or secure commercial employment. Compliance obligations should be assessed against the relevant laws and guidance, with qualified legal advice where necessary.
Israel-Hamas War and Wider Middle East Security Risks

The Israel-Hamas war, which began in October 2023, added another layer of geopolitical uncertainty to the Middle East. The conflict affected regional security assessments and raised concerns about the potential disruption of nearby maritime routes and energy infrastructure.
The conflict also formed part of the context for attacks on commercial shipping in the Red Sea by the Houthi movement in Yemen. These attacks led many shipping companies to divert vessels away from the Red Sea and Bab el-Mandeb Strait, using the longer route around the Cape of Good Hope.
The resulting disruption affected voyage distances, vessel schedules, fuel consumption and freight-market conditions. It also demonstrated how a regional conflict can influence shipping operations well beyond the immediate area of hostilities.
The Red Sea situation has changed over time. By October 2026, traffic through the Suez Canal had increased to 1,338 reported transits, up 63% year on year. However, this remained 34% below the pre-crisis level. Bab el-Mandeb recorded 1,363 transits, up 43% year on year but still 46% below the pre-crisis level. These figures cover cargo-carrying vessels above 10,000 deadweight tonnes and represent reported transits, not total cargo volume or trade value.
The increase in transit counts does not establish that the route has returned to normal operating conditions. Lloyd's List Intelligence's November 12, 2026 report noted that the return of mainline container services was continuing while renewed Houthi attacks underlined the security risks facing carriers restoring Red Sea services. It also reported that approximately half of containership transits were operating with vessel-tracking systems disabled, complicating the interpretation of reported traffic data.
The Red Sea disruption illustrates the relationship between geopolitical risk and shipping economics. A shorter route may offer lower voyage costs and faster transit times, but those advantages must be assessed against security, insurance and operational risks.
What Changed in Global Shipping Since 2023?
The shipping industry has experienced several significant changes since the article was originally published in December 2023. The Red Sea crisis, changes in trade policy, sanctions developments and the transition towards alternative fuels have affected shipping routes, freight markets and vessel operating decisions.
Red Sea Disruption and Suez Canal Rerouting
Attacks on commercial vessels in the Red Sea from late 2023 led many shipping companies to suspend or limit Suez Canal transits. Numerous operators diverted vessels around the Cape of Good Hope, adding distance and voyage time to services connecting Asia, Europe and other markets.
The longer route increased fuel consumption and reduced the effective availability of container ship capacity. A vessel spending more days completing a voyage cannot be redeployed as quickly, even when the number of ships in the global fleet remains unchanged.
UNCTAD's Review of Maritime Transport 2025 reported that rerouting pushed global maritime ton-miles up by 5.9% in 2024, nearly three times the growth in cargo volume. This distinction matters: the increase reflected longer transport distances, not an equivalent increase in the quantity of cargo traded.
The same report noted that by May 2025, tonnage passing through the Suez Canal remained 70% below 2023 levels. This illustrates the scale of the disruption during the period covered by the report.
By October 2026, Suez and Bab el-Mandeb traffic had recovered from their crisis lows, but remained below pre-crisis levels. Lloyd's List Intelligence reported 1,338 Suez transits in October, compared with a pre-crisis monthly average of approximately 2,009 transits from January to November 2023.
The recovery has not been uniform across vessel types or operators. Some container carriers have resumed Suez services, while others continue to assess security exposure, insurance conditions and the commercial benefits of the shorter route.
Freight Rates, Fuel Consumption and Insurance Costs
The Red Sea disruption affected shipping economics beyond the cost of taking a longer route. Longer voyages increased fuel consumption, required additional vessel capacity and complicated schedule planning. Port congestion and changes to vessel deployment added further pressure.
UNCTAD's Review of Maritime Transport 2025 reported that container spot and charter rates approached COVID-19-era peaks by mid-2024 before moderating. The Shanghai Containerized Freight Index averaged 2,496 points in 2024, an increase of 149% compared with 2023. The report also described continued volatility into 2025 amid tariff announcements and geopolitical risks.
War-risk insurance premiums and other insurance conditions also became relevant to voyage decisions. UNCTAD's 2024 review identified increased war-risk insurance premiums among the additional costs associated with disruption to major maritime routes. The actual premium applicable to a vessel depends on its route, flag, ownership, trading history, insurer and the prevailing risk assessment.
The impact on vessel economics varies by segment. Container ships may face changes in service rotations and charter availability. Tankers may be affected by changes in cargo origin, destination and sanctions exposure. Dry bulk vessels may experience different demand and freight-rate effects depending on the commodities and trade routes involved.
It is therefore important to distinguish between freight-market movements, vessel operating costs and insurance expenses. They are related, but they are not interchangeable measures of the financial impact of a disruption.
US-China Trade Policy and Tariff Changes
Trade tensions between the United States and China have continued to affect international commerce since 2023. Tariffs, export controls and other trade restrictions can influence sourcing decisions, manufacturing locations and the direction of cargo flows.
The Congressional Research Service's August 18, 2026 overview reported that US and Chinese tariff actions have continued since 2025. It also described export controls, market restrictions and retaliatory measures, alongside discussions between the two governments. Some measures have been paused or adjusted, but the wider trade-policy relationship remains subject to change.
For shipping companies, the effects can include shifts in container volumes, changes in port calls, adjustments to trade lanes and changes in demand for vessel capacity. However, tariffs do not automatically translate into lower shipping demand. Importers and exporters may change suppliers, redirect trade or move production to other markets.
The WTO's finding that 72% of global merchandise trade was conducted on MFN tariff terms at the end of July 2026 provides additional context. It indicates that a substantial share of trade continues under the multilateral MFN framework, even as tariff actions and preferential arrangements influence other trade flows.
Alternative Fuels and the Infrastructure Gap
The maritime energy transition has also progressed since 2023. LNG, methanol, ammonia and hydrogen are receiving attention in vessel design and fuel strategies, but their commercial readiness differs.
Lloyd's Register reported in November 2026 that alternative-fuel-capable ships represented 47% of global orderbook tonnage. However, the availability of bunkering infrastructure remains uneven: its report identified 222 ports offering LNG bunkering, 25 offering methanol bunkering and one completed commercial ammonia bunkering operation at the time of publication.
This difference between vessel orders and fuel infrastructure is important for shipowners. A vessel's ability to use an alternative fuel does not guarantee that the fuel will be available at the ports it regularly visits. Fuel price, production pathway, safety requirements and regulatory treatment also influence the commercial case.
For existing vessels, retrofits may involve capital expenditure, downtime and technical limitations. For newbuildings, owners must consider the risk that a selected fuel pathway or engine configuration may become less competitive as technology and regulation develop.
The transition is therefore a long-term fleet and infrastructure decision rather than a simple change in bunker fuel.
What These Changes Mean for Shipping Economics
Developments since 2023 demonstrate how economic and geopolitical conditions can affect the shipping industry through several connected variables:
Freight rates: Changes in cargo demand, available vessel capacity, route length and market sentiment can affect freight rates.
Fuel and operating costs: Longer voyages, fuel-price changes and additional security requirements can increase voyage expenses.
Vessel utilisation: Delays, diversions and changes in port schedules can affect the time a vessel spends earning revenue.
Insurance: War-risk premiums and coverage conditions may change in response to security assessments, vessel characteristics and trading areas.
Regulatory compliance: Sanctions, emissions rules and trade restrictions can affect where a vessel may trade and which services it can access.
Asset values: Changes in earnings expectations, operating costs, vessel age, regulatory exposure and market liquidity can influence vessel valuations.
These factors interact. For example, a longer voyage may increase ton-mile demand and reduce the effective availability of vessels in a particular trade. At the same time, the additional fuel, insurance and crew costs may reduce the economic benefit to the shipowner.
It is therefore important to assess both revenue potential and cost exposure rather than treating any single market indicator as a complete measure of vessel performance.
Conclusion
The global shipping industry is shaped by the interaction of economics and geopolitics. Economic forces influence trade demand, freight rates, vessel supply, fuel costs and operating efficiency. Geopolitical developments affect trade relationships, maritime security, sanctions, port access and the reliability of shipping routes.
The historical development of containerization transformed cargo handling and global supply chains. The transition towards alternative fuels is now creating new technical, regulatory and capital requirements for vessel owners. At the same time, trade policy tensions and regional conflicts continue to change the commercial environment in which shipping companies operate.
The COVID-19 pandemic, the Russia-Ukraine war and disruption in the Red Sea demonstrate how quickly external events can affect maritime operations and global trade. They also show why shipping economics cannot be understood through freight rates or cargo volumes alone.
For maritime professionals and investors assessing vessel-backed assets, the relevant analysis extends beyond market conditions. It includes vessel characteristics, trading routes, charter arrangements, operating expenses, insurance, regulatory exposure and the legal structure through which an economic interest is represented.
Tokenization may provide a framework for representing certain asset-related or contractual interests. However, a token does not automatically confer vessel ownership, equity, security status or entitlement to cash flows. Those rights depend on the applicable legal and contractual arrangements.
A rigorous assessment must therefore distinguish the underlying vessel, the vessel-owning entity, the issuer, the contractual rights and the economic exposure represented by any instrument. Understanding these distinctions is essential when evaluating maritime assets in a market shaped by economic cycles, geopolitical developments and regulatory change.
Frequently Asked Questions
How do economics affect the global shipping industry?
Economic conditions influence shipping through international trade demand, freight rates, fuel prices, vessel capacity and operating costs. Changes in these factors affect shipping activity, vessel deployment and the cost of transporting goods.
How does geopolitics affect global shipping routes?
Geopolitical conflicts, maritime security threats and trade restrictions can disrupt established shipping routes. Shipping companies may divert vessels around affected areas, increasing voyage distances, transit times, fuel consumption and operating costs.
How did the Red Sea crisis affect the shipping industry?
Attacks on commercial vessels in the Red Sea led many shipping companies to divert vessels away from the Suez Canal and Bab el-Mandeb Strait, using the longer route around the Cape of Good Hope. These diversions increased voyage distances, affected vessel schedules and contributed to changes in freight rates and shipping capacity.
How do trade wars and tariffs affect maritime trade?
Trade wars and tariffs can change the cost and direction of international trade. Businesses may adjust sourcing locations, suppliers and shipping routes in response to trade restrictions. These changes can influence cargo volumes, port activity and demand for shipping services.
How are alternative fuels changing the shipping industry?
Alternative fuels such as LNG, methanol, ammonia and hydrogen are influencing vessel design, propulsion technology and emissions strategies. Their adoption depends on factors including fuel production, availability, bunkering infrastructure, safety requirements, vessel compatibility and lifecycle emissions.
References
Lloyd's Register, Alternative-fuel ships outpace port readiness, new LR report finds, November 2, 2026. https://www.lr.org/en/knowledge/press-room/press-listing/press-release/2026/alternative-fuel-ships-outpace-port-readiness-new-lr-report-finds/
International Maritime Organization, Guidelines on Life Cycle GHG Intensity of Marine Fuels (2024 LCA Guidelines). https://www.imo.org/en/ourwork/environment/pages/lifecycle-ghg---carbon-intensity-guidelines.aspx
World Trade Organization, Share of world merchandise trade on MFN tariff terms, data through July 2026. https://www.wto.org/english/res_e/reser_e/world_merchandise_trade_on_mfn_tariff_e.htm
Council of the European Union, EU sanctions against Russia: questions and answers. https://www.consilium.europa.eu/en/policies/sanctions-against-russia-explained/
Council of the European Union, 21st package of sanctions: EU hits Russian energy, financial services and crypto hard, July 23, 2026. https://www.consilium.europa.eu/en/press/press-releases/2026/07/23/21st-package-of-sanctions-eu-hits-russian-energy-financial-services-and-crypto-hard/
Lloyd's List Intelligence, Red Sea Brief – 12 November 2026, November 12, 2026. https://www.lloydslistintelligence.com/resources/blog/red-sea-brief---12-november-2026
UN Trade and Development (UNCTAD), Review of Maritime Transport 2025: Staying the course in turbulent waters. https://unctad.org/publication/review-maritime-transport-2025
UN Trade and Development (UNCTAD), Review of Maritime Transport 2025, Chapter III: Freight rates and maritime transport costs. https://unctad.org/system/files/official-document/rmt2025_en.pdf
UN Trade and Development (UNCTAD), Review of Maritime Transport 2024: Navigating maritime chokepoints. https://unctad.org/publication/review-maritime-transport-2024
Congressional Research Service, U.S.-China Tariff Actions Since 2018: An Overview, updated August 18, 2026. https://www.everycrsreport.com/reports/IF12990.html
Regulatory disclosure: Shipfinex FZCO holds VARA In-Principle Approval (IPA/26/01/002) for Virtual Asset Broker-Dealer Activity. This is an In-Principle Approval, not a full operational licence. Shipfinex is not authorised to commence operations or conduct virtual asset activities until it obtains final authorisation from the Virtual Assets Regulatory Authority (VARA). This article is for informational purposes only and does not constitute legal advice, regulatory guidance, or an offer or invitation to deal in virtual assets or securities. All investments carry significant risk, including the potential for total loss. This is a high-risk asset. See the full Risk Disclosure Statement.

Suraz Troy Kottakki
Founder & COO
Suraz Troy Kottakki is the Founder and Chief Operating Officer of Shipfinex. His work focuses on maritime finance, digital asset infrastructure and structures through which Maritime Asset Tokens may represent specified economic exposure linked to vessel-owning Special Purpose Vehicles (SPVs). The rights and obligations associated with any MAT are determined by the relevant legal and offering documents.
LinkedIn: https://www.linkedin.com/in/szka


